
Best Virtual Terminal for Small Businesses 2026-2026: The Zero-Fee Guide
Published:
What if you could stop paying for the privilege of accepting your customers’ money? Small businesses that implement a cash discount model see average annual savings of approximately $7,500, yet many owners still struggle to find the best virtual terminal for small businesses 2025 2026 that doesn’t eat their profits. While legacy providers like Square often charge 3.5% plus 15¢ for manual entry, these costs are no longer an unavoidable reality of doing business in 2026. You shouldn’t have to sacrifice your thin margins just to offer the convenience of remote payments.
We understand the frustration of navigating hidden monthly fees and the constant pressure of PCI compliance. This guide reveals how to eliminate processing costs entirely by transforming any computer or tablet into a secure, fee-free payment hub. You’ll discover how automated surcharge engines provide a path to $0 processing fees while maintaining strict adherence to state laws. We will break down the essential features of modern gateways, from AI-driven fraud prevention to omni-channel tools that turn every transaction into a protected asset for your business.
Key Takeaways
- Learn why the best virtual terminal for small businesses 2025 2026 is a browser-based gateway that replaces bulky hardware with secure, tokenized payment entry.
- Discover how to implement a surcharge or dual pricing model to pass convenience costs to cardholders and achieve $0 in processing fees legally.
- Understand how Level 2 and Level 3 data processing can significantly lower transaction rates for B2B businesses by providing more detailed transaction info.
- Get a step-by-step method to audit your current effective rate and verify that your provider handles zero-fee compliance under state laws.
- Explore how AI-driven fraud prevention and smart pricing engines automate compliance and protect your margins without manual intervention.
Table of Contents
- What Makes the Best Virtual Terminal for Small Businesses in 2026?
- Essential Features for Modern Payment Gateways
- Traditional Processing vs. Zero-Fee Surcharge Models
- How to Select the Best Provider for Your Business
- Why Strictly is the Top Virtual Terminal Choice for 2026
What Makes the Best Virtual Terminal for Small Businesses in 2026?
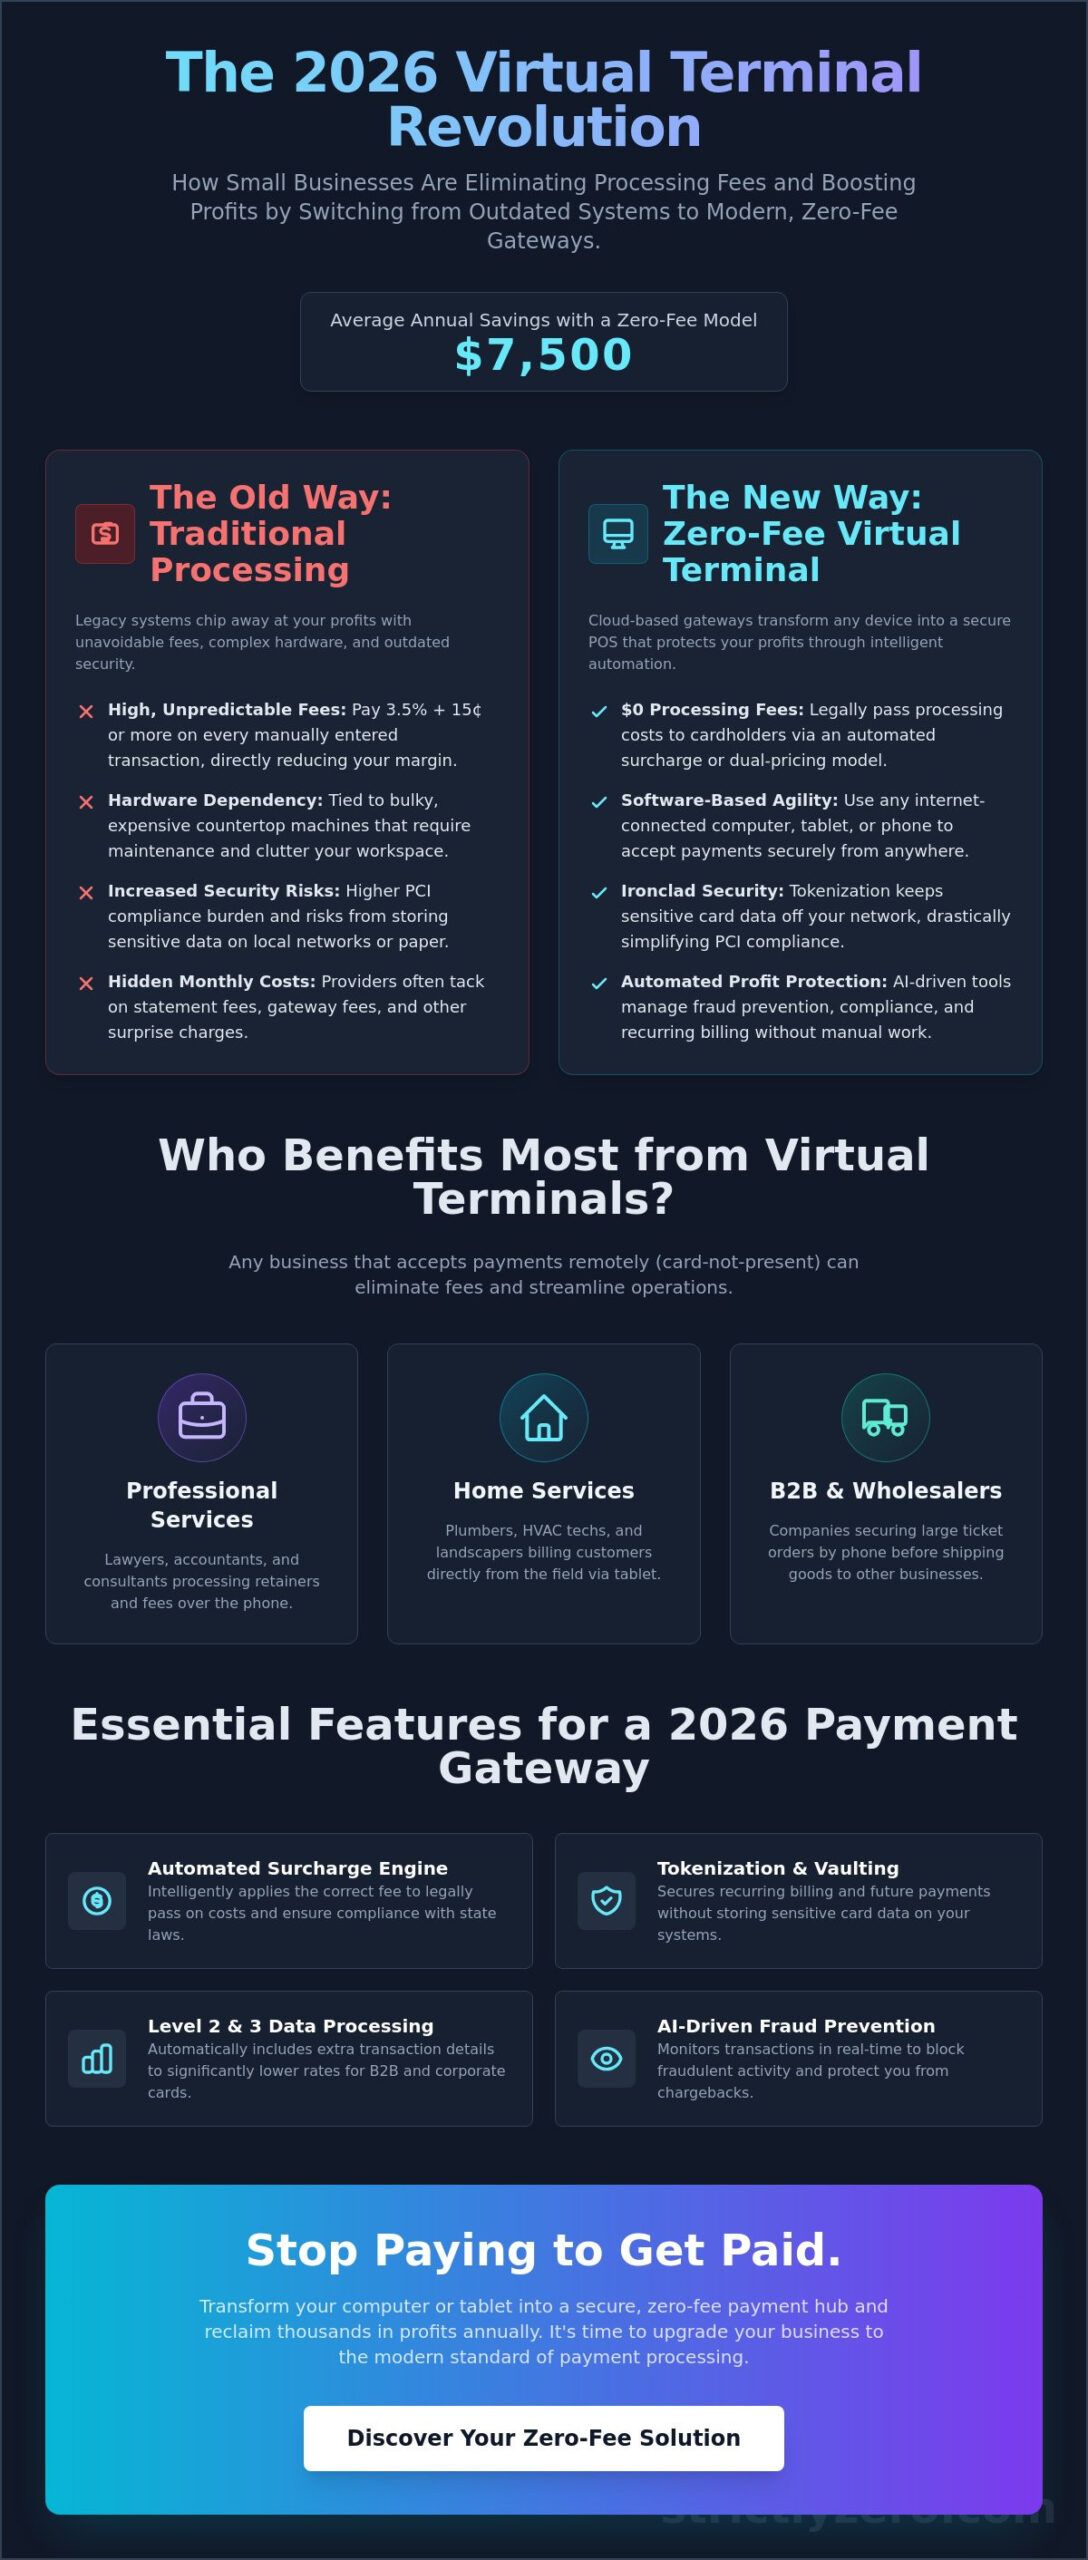
The 2026 business environment demands agility. For service-based companies, the era of the bulky, countertop credit card machine is fading. Instead, the best virtual terminal for small businesses 2025 2026 has become a browser-based gateway that turns any internet-connected computer or tablet into a powerful point of sale. This shift isn’t just about convenience; it’s about profit. Modern platforms have evolved from simple data entry screens into automated profit protection engines that handle compliance and fee management without human error.
A virtual terminal is a cloud-based interface for remote payment processing. For a deeper technical look at the history and standard functions, you can read more about What is a Virtual Terminal? via Wikipedia. By using these portals, merchants can securely type in credit card details provided over the phone or through mail order, ensuring they never lose a sale because a customer isn’t physically present.
To better understand this concept, watch this helpful video:
The Remote Payment Revolution
The way customers pay is changing fast. Phone, mail, and invoice-based transactions are driving significant growth for small firms that don’t operate a traditional storefront. Storing card numbers on sticky notes or paper ledgers is a massive security risk that leads to data breaches and heavy fines. Cloud-based entry solves this by using tokenization, where sensitive data stays off your local network. Many businesses are now transitioning from fragmented legacy hardware to a unified ecommerce payment processing platform. This consolidation allows you to manage remote, online, and in-person data in one dashboard.
Who Benefits Most from a Virtual Gateway?
Not every business needs a physical card reader. In fact, for many, it’s an unnecessary expense that clutters the workspace. The best virtual terminal for small businesses 2025 2026 serves specific niches that rely on remote communication:
- Professional services: Lawyers, accountants, and consultants use virtual terminals to process retainers and monthly fees while the client is on the phone.
- Home services: HVAC techs, plumbers, and landscapers can bill directly from the field using a tablet, eliminating the need to wait for a check in the mail.
- Wholesalers and B2B: Companies handling large-ticket orders via phone can input data directly into the gateway to secure payment before shipping goods.
These industries prioritize security and speed. By moving away from physical hardware, they reduce maintenance costs and focus on their core operations while the software handles the heavy lifting of payment security.
Essential Features for Modern Payment Gateways
Selecting the best virtual terminal for small businesses 2025 2026 requires looking beyond a simple input field. Modern gateways now act as intelligence layers that optimize every transaction for both speed and cost. For B2B merchants, Level 2 and Level 3 data processing is a non-negotiable feature. By including specific purchase details like tax amounts and invoice numbers, businesses can qualify for significantly lower interchange rates from card networks. This is a common highlight in reviews for the best virtual terminal for small businesses, as it directly impacts the bottom line for high-ticket service providers who deal with corporate cards.
Tokenization provides another layer of protection that’s vital in 2026. It ensures that sensitive cardholder data never touches your local network or physical servers. Instead, the data is replaced by a unique digital identifier. This significantly reduces your PCI compliance scope, making the annual audit process much simpler and less expensive. Additionally, automated recurring billing is essential for subscription models. It handles failed payments and card updates without manual intervention, which is a major upgrade from the manual entry methods of the past.
Security and PCI Compliance in 2026
In 2026, end-to-end encryption is just the starting point. The real value lies in how a gateway minimizes risk through hosted payment fields. These fields ensure that data is captured directly by the processor, keeping your business out of the line of fire during a potential breach. AI-driven fraud prevention has also become more sophisticated. It analyzes hundreds of data points in milliseconds to block suspicious remote transactions before they’re even processed. This proactive approach is vital for businesses that don’t have the luxury of seeing a physical card or ID.
API-First Design and Customization
Flexibility is key for growing firms. A gateway should offer an payment processing platform for ISOs and developers that supports deep integration. This allows you to sync virtual terminal data with your existing CRM or accounting software automatically. You won’t have to spend hours on manual data entry or reconciliation at the end of the month.
The most advanced platforms now include a “Smart Pricing” engine. This feature automatically adjusts transaction costs based on the customer’s state laws, ensuring compliant surcharging every time. If you’re ready to modernize your workflow, exploring a surcharge-ready virtual terminal can help you recover thousands in annual fees. By using developer-friendly hooks, you can build custom workflows that bridge the gap between your online links and your back-office operations.
Traditional Processing vs. Zero-Fee Surcharge Models
Traditional credit card processing acts like a hidden tax on your growth. For decades, small businesses accepted that losing 3% of every sale was just the cost of doing business. However, the best virtual terminal for small businesses 2025 2026 flips this script by moving the cost of convenience away from the merchant. While major publications like Forbes often list the best virtual terminal for small businesses based on flat-rate pricing, those “simple” rates still eat into thin margins. A surcharge program can reduce effective processing rates to 0% for the merchant by adding a small fee to credit card transactions at the point of sale.
Dual pricing offers another transparent alternative. This model presents customers with two distinct prices: one for cash or debit, and one for credit cards. It gives the buyer the choice while ensuring the business owner doesn’t lose money on the transaction. Unlike traditional models where the merchant pays the bank for every swipe, these modern strategies allow you to keep 100% of your sticker price. It’s a fundamental shift in how revenue is calculated, especially for high-volume service providers. U.S. merchants paid $187.20 billion in card processing fees in 2024, a cost that most small firms can no longer ignore if they want to remain competitive.
The Math of Zero-Fee Processing
The financial impact of switching models is staggering when you look at the annual numbers. Consider a business with a $10,000 monthly processing volume. Under a traditional 3% flat-rate plan, that business loses $300 every month, or $3,600 per year. With a compliant surcharge model, that $300 stays in the business bank account. These savings are often reinvested into digital marketing or inventory, providing a competitive edge. A Smart Pricing Engine is critical here; it must detect debit cards instantly to ensure you don’t accidentally apply a surcharge to them, which would violate network rules and lead to potential fines.
Automated Compliance and State Laws
Regulatory requirements for surcharging are a moving target. In 2026, the map of U.S. surcharge laws remains complex, with specific disclosure and registration rules varying by state. Attempting to manage these rules manually is a massive liability risk. If you get it wrong, you face heavy penalties from card networks. Strictly’s engine solves this by automatically adjusting the transaction based on the merchant’s physical location and the customer’s card type. This automation ensures you stay on the right side of the law without having to become a legal expert yourself. It’s about protecting your profit while staying completely compliant with the ever-changing legal landscape.
How to Select the Best Provider for Your Business
Choosing the best virtual terminal for small businesses 2025 2026 isn’t just about picking a recognizable brand. It’s a strategic decision that affects your daily cash flow and long-term scalability. The selection process should move beyond superficial features and focus on the total impact on your bottom line. Follow these five steps to ensure you partner with a provider that prioritizes your profit.
- Step 1: Audit your “effective rate.” Divide your total monthly processing fees by your total sales volume. If you’re paying more than 3% in a traditional model, you’re losing significant revenue that could be reclaimed.
- Step 2: Verify legal compliance. Ensure the provider can handle zero fee credit card processing legally across different states. This requires a system that can distinguish between credit and debit cards instantly.
- Step 3: Test the interface. A slow or confusing terminal leads to errors and frustrated staff. The software should be fast enough to handle a high-volume office without lagging.
- Step 4: Scan for hidden junk fees. Look closely at the fine print for statement fees, batch fees, or annual PCI compliance charges. These small additions can quietly add $50 to $100 to your monthly bill.
- Step 5: Demand human support. When a payment fails or a system goes down, you don’t have time to wait for an AI chatbot. Ensure your provider offers 24/7 access to real human experts.
Evaluating the Total Cost of Ownership
A “free” virtual terminal often hides higher per-transaction markups that cost you more in the long run. You must look at the total cost of ownership over a full year of operation. Many legacy providers use “contract traps” like liquidated damages or three-year exclusivity clauses to keep you from switching to better technology. In the rapidly changing 2026 market, month-to-month agreements are the gold standard. They force the processor to earn your business every single month through high-quality service rather than legal threats.
Integration and Scalability
Your terminal shouldn’t exist in a vacuum. It should be the foundation of a complete omni-channel payment processing system. This means your remote phone orders, mobile app payments, and “Pay by Link” features all flow into a single, unified dashboard. If you’re working with an ISO or a custom developer, ask if the gateway offers robust API hooks for future growth. If you are ready to stop losing money to outdated fee structures, you can get started with a zero-fee terminal today and see an immediate boost in your monthly margins.
Why Strictly is the Top Virtual Terminal Choice for 2026
Strictly stands apart from traditional processors by treating payment technology as a tool for growth rather than a tax on your labor. While other providers focus on shaving off fractions of a percentage point, we built the best virtual terminal for small businesses 2025 2026 around a zero-fee mission. Our platform doesn’t just process cards; it protects your bottom line using a proprietary Smart Pricing Engine. This engine is the brain of our system, automatically identifying card types and applying state-specific surcharge rules in real-time. This ensures your business remains 100% compliant without you ever having to look up a local regulation or network update.
Our omni-channel dashboard brings every aspect of your sales together. Whether you’re entering a phone order into the virtual terminal, sending a digital invoice, or reviewing mobile sales, all your data lives in one secure place. You get a clear, transparent view of your revenue without the clutter of physical hardware or fragmented reports from multiple vendors. We prioritize transparency and reliability, ensuring that the price you see on your dashboard is the money that actually hits your bank account.
Profit Protection as a Service
We view our relationship with merchants as a partnership in profit protection. By eliminating the “Merchant Tax” discussed in previous sections, we help small firms recover thousands of dollars that would otherwise go to bank fees. For instance, a typical service-based business processing $50,000 a month can save approximately $15,000 per year by switching from a standard 3% flat-rate model to our zero-fee platform. These are real funds that you can reinvest into your team or your marketing. You can see your own potential savings by using our cost of credit card processing calculator for an instant, data-driven estimate based on your current volume.
Getting Started with Strictly
Transitioning to a new processor shouldn’t be a headache. Our onboarding team is designed for speed, often getting your new virtual terminal live in under 24 hours. We don’t just hand you the keys and walk away. We provide the resources you need to train your staff on surcharge transparency, ensuring they can confidently communicate the benefits of dual pricing to your customers. This human-centric approach is why so many firms consider us the best virtual terminal for small businesses 2025 2026. If you’re tired of watching your hard-earned margins disappear into thin air, it’s time to make a change. Switch to Strictly and eliminate your processing fees today. Our merchant-first support team is ready to help you reclaim your revenue and scale your business with confidence.
Reclaim Your Revenue with Smarter Processing
The landscape of payment processing has shifted. Staying with traditional models means continuing to lose a portion of every sale to the $187.20 billion fee pool that drained merchant accounts in 2024. Finding the best virtual terminal for small businesses 2025 2026 is no longer just about ease of use; it’s about reclaiming your revenue. By moving to a zero-fee surcharge model, you effectively reduce your processing rates to $0 while our Smart Pricing Engine handles 100% of the compliance requirements automatically.
You’ve seen how legacy hardware and hidden junk fees erode your margins. It’s time to leverage technology that works for you, not against you. With omni-channel capabilities and AI-driven fraud protection, your business can scale securely without the weight of unnecessary transaction costs. Don’t let high fees dictate your growth potential any longer. You have the tools to turn any device into a secure profit center.
Eliminate Your Processing Fees with Strictly’s Virtual Terminal and start seeing your true earnings in your bank account. Your business deserves a partner that prioritizes your success over bank profits.
Frequently Asked Questions
Is a virtual terminal safe for taking credit card numbers over the phone?
Yes, virtual terminals are safe because they use end-to-end encryption and tokenization to protect sensitive data. These security features ensure that card numbers are never stored locally on your computer or tablet. By using a secure gateway, you meet PCI DSS requirements without needing physical hardware. This is much safer than writing card details on paper or storing them in unencrypted digital files.
Do I need a merchant account to use a virtual terminal in 2026?
You definitely need a merchant account to process payments through a virtual terminal. The terminal acts as the software interface, while the merchant account is the financial account where your funds are held before being deposited. Some providers offer a combined setup, but having a dedicated merchant account often provides better stability and lower long-term costs for growing businesses.
Can I use a virtual terminal on my smartphone or tablet?
You can use a virtual terminal on any smartphone or tablet with a modern web browser. Since these portals are cloud-based, they don’t require specific app downloads to function. This flexibility allows field service workers to take payments on the go. It effectively turns any mobile device into a secure payment hub without the need for additional card-reading hardware.
What is the difference between a payment gateway and a virtual terminal?
A payment gateway is the underlying technology that routes transaction data, while a virtual terminal is the user-facing dashboard. Think of the gateway as the “pipes” and the terminal as the “faucet.” While a gateway might power an online store’s checkout page, the virtual terminal is the specific tool you use to manually enter card details for phone or mail orders.
Are surcharge programs legal in all 50 states for virtual terminals?
Surcharge programs are legal in most states, but specific disclosure and registration requirements vary. As of May 2026, states like Massachusetts and Connecticut still maintain specific restrictions on certain surcharge models. The best virtual terminal for small businesses 2025 2026 should include a smart engine that automatically detects the customer’s location. This ensures you never apply a fee that violates local regulations.
How much does a typical virtual terminal cost for a small business?
Costs vary depending on the provider’s pricing model. For example, Square charges 3.5% plus 15¢ per keyed-in transaction on their standard plan. Helcim uses interchange-plus pricing, which is Interchange + 0.50% + 25¢ for volumes up to $50,000 per month. Choosing a zero-fee model allows you to bypass these per-transaction costs entirely by passing the convenience fee to the cardholder.
Can a virtual terminal handle recurring billing and subscriptions?
Modern virtual terminals are built to handle recurring billing and complex subscription schedules easily. You can securely “vault” a customer’s card information using tokenization for future use. This allows you to set up automated weekly or monthly charges. It reduces the administrative burden of chasing down payments and improves your monthly cash flow consistency.
What happens if a customer disputes a transaction processed via virtual terminal?
If a customer disputes a transaction, the process follows standard card network rules for “card-not-present” sales. Since you didn’t swipe a physical card, the burden of proof for the sale rests on you as the merchant. You’ll need to provide digital receipts, signed contracts, or delivery confirmation. AI-driven fraud prevention tools help by flagging high-risk transactions before they result in a costly chargeback.