
How to Accept Payments Online Without a Website: The 2026 Merchant Guide
Published:
Skipping the traditional e-commerce storefront might be the most profitable move your business makes this year. While many entrepreneurs assume a digital presence requires a complex site, learning how to accept payments online without a website is actually the fastest path to a lean, high-margin operation. You’re likely tired of paying high transaction fees for manual entry or worrying about the security risks of taking card info over the phone. It’s frustrating when simple billing feels like a high-risk chore, especially with the strict PCI DSS 4.0 standards now in full effect.
Whether you prefer the control of a terminal or the agility of a link, the goal remains the same. You want a secure, professional way to get paid. For those selling through online classifieds or marketplaces, TrustEcho provides an additional layer of protection for every transaction. By balancing these two methods, you can tailor your workflow to match how your customers prefer to buy. This flexibility is the secret to how to accept payments online without a website while still looking like a Fortune 500 company.
We agree that getting paid shouldn’t be this complicated or expensive. This guide will show you how to leverage advanced virtual terminals and professional invoicing to get your money immediately while maintaining elite security. You’ll discover how to protect your revenue from the $66.4 billion eCommerce fraud threat using AI-driven prevention and how a dual pricing engine can effectively eliminate your processing costs. From omni-channel tools to secure payment links, we’re breaking down the most efficient ways to get paid in 2026.
Key Takeaways
- Learn exactly how to accept payments online without a website by utilizing professional virtual terminals that turn any device into a secure billing hub.
- Navigate the complexities of PCI DSS 4.0 compliance and protect your revenue with AI-driven fraud prevention designed for card-not-present transactions.
- Discover how a surcharge and dual pricing engine can offset high merchant fees, allowing you to keep 100% of your service-based margins.
- Compare the speed of instant payment links against the robustness of virtual terminals to find the most efficient workflow for your specific business model.
- Streamline your operations with omni-channel processing tools that provide immediate access to funds and professional invoicing without the overhead of a digital store.
Table of Contents
- Modern Methods for Accepting Online Payments Without a Website
- Virtual Terminals vs. Payment Links: Which Is Right for You?
- Ensuring Security and PCI Compliance in 2026
- Calculating the Real Cost: Eliminating Processing Fees
- Scaling Your Business with Strictly: The All-in-One Solution
Modern Methods for Accepting Online Payments Without a Website
The payment landscape in 2026 has shifted toward speed and simplicity. You don’t need a complex e-commerce store to participate in the global economy. In fact, many service-based businesses are ditching traditional websites to avoid maintenance costs and technical debt. Learning how to accept payments online without a website is no longer just a workaround for small startups. It’s a strategic choice for professionals who value direct, frictionless transactions. Many entrepreneurs find that how to accept payments online without a website is actually simpler and more secure than managing a full digital storefront.
To better understand this concept, watch this helpful video:
Modern online payment systems now rely on three main pillars: digital payment links, robust invoicing, and virtual terminals. While some providers might focus on just one of these tools, the real power lies in an omni-channel payment processing platform. This unified approach ensures that whether you’re sending a link via text or keying in a card manually, all your data, fraud prevention, and reporting live in one place. It eliminates the silos that often lead to accounting nightmares and security gaps.
The Rise of the Virtual Gateway
A virtual gateway is a secure web-based portal for transaction management that replaces the need for a physical storefront. Think of it as your digital command center. Instead of paying for hosting and web design, you use this gateway to process card-not-present transactions safely. The transition from physical swiping to digital entry has accelerated because it allows you to close deals anywhere, from a client’s driveway to a remote consulting session, without carrying bulky hardware.
Why Businesses Choose Non-Website Payments
Service industries like construction, legal consulting, and specialized contracting are leading this movement. These businesses often deal with high-ticket items where a “Buy Now” button on a website feels impersonal. By bypassing a traditional site, you benefit from lower overhead and a significantly faster time-to-market. You can start billing clients the same day you set up your account. This flexibility allows you to meet customers where they are, whether that’s through a quick SMS link, a professional email invoice, or a direct message on social media. It’s about making the payment process as mobile and agile as your business.
Virtual Terminals vs. Payment Links: Which Is Right for You?
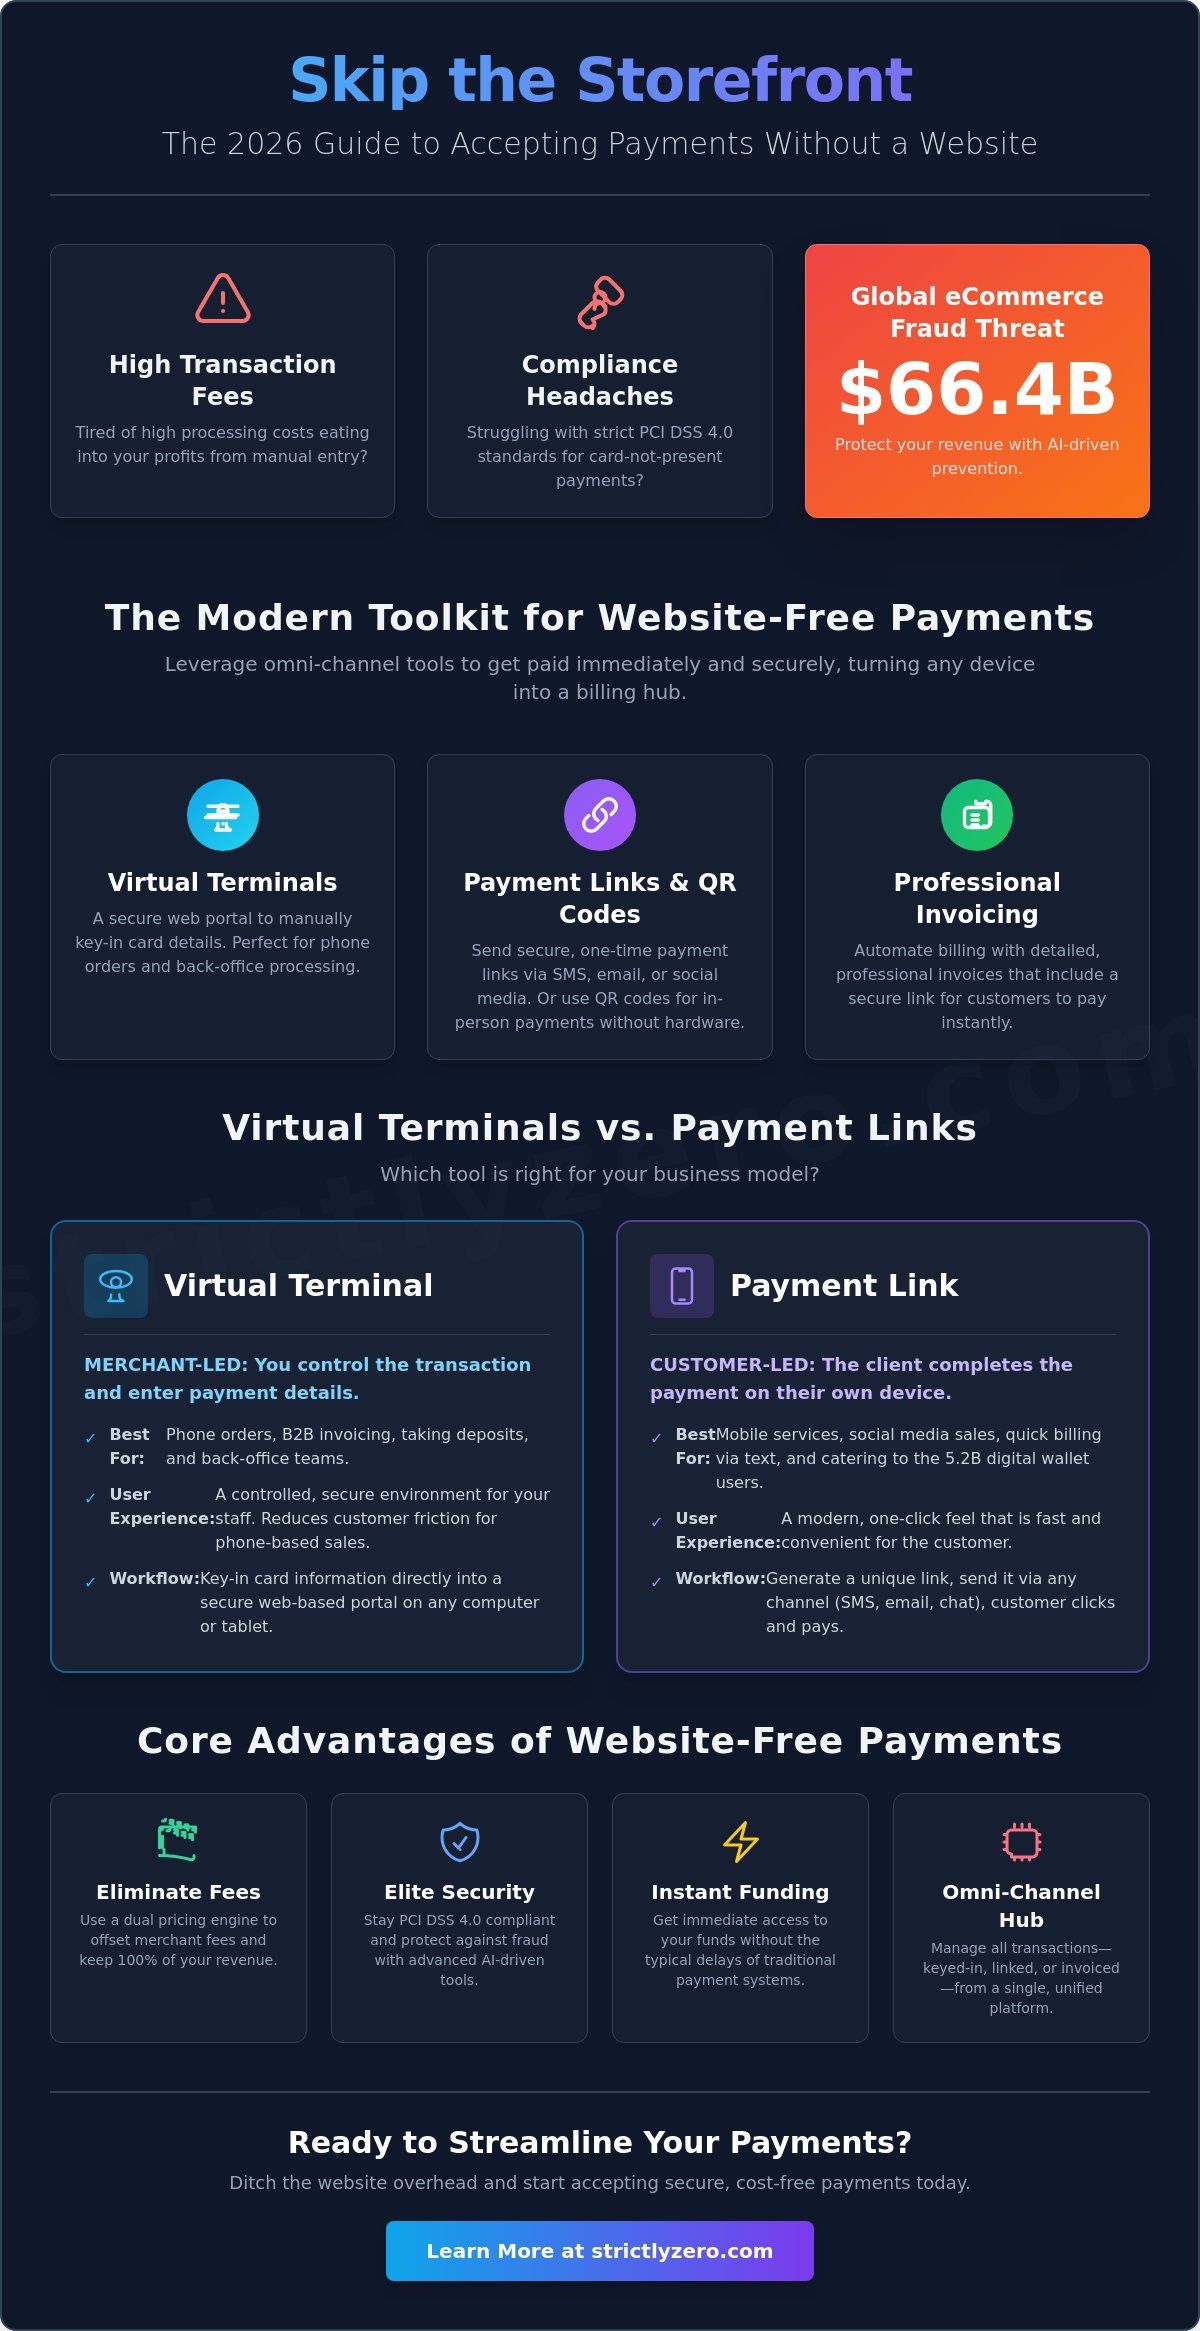
Choosing the right tool is the first step toward mastering how to accept payments online without a website. While both methods bypass the need for a traditional storefront, they serve different operational needs. A virtual terminal is merchant-led, meaning you take the lead in entering payment details. In contrast, payment links are customer-led, allowing the buyer to complete the transaction on their own device. Understanding this distinction helps you maintain professional boundaries while keeping your cash flow steady.
When to Use a Virtual Terminal
Virtual terminals are the gold standard for phone orders and professional services. If you’re a consultant or a contractor taking a deposit over the phone, you can key in card data directly into a secure web portal. This method is highly effective for administrative tasks because it allows for immediate verification. You don’t have to wait for a customer to check their email. These systems are also built for recurring billing. You can securely save payment profiles to automate monthly retainers or subscription fees without ever storing sensitive card numbers on your local hard drive, which keeps you compliant with PCI DSS 4.0 standards.
Maximizing the Power of Payment Links
Payment links are the ultimate tool for speed and flexibility. You can create a unique link for a specific service package and drop it directly into a WhatsApp chat, an SMS, or a social media DM. This eliminates the friction of a traditional checkout process. When a customer clicks the link, they see a professional, branded interface where they can pay via credit card or digital wallet in seconds. This method is particularly effective for high-volume service businesses that want to send quick follow-up bills after a job is completed. Finding a provider that offers a unified virtual terminal and invoicing platform ensures you have the right tool for every client interaction.
Whether you prefer the control of a terminal or the agility of a link, the goal remains the same. You want a secure, professional way to get paid. By balancing these two methods, you can tailor your workflow to match how your customers prefer to buy. This flexibility is the secret to how to accept payments online without a website while still looking like a Fortune 500 company.
Ensuring Security and PCI Compliance in 2026
Security is the foundation of how to accept payments online without a website. When you don’t have a physical storefront, you’re operating entirely in the Card-Not-Present (CNP) space. This category remains a primary target for bad actors. In 2026, eCommerce fraud is projected to reach $66.4 billion globally. This makes robust protection a necessity rather than an optional feature. You’re responsible for keeping customer data safe even if you don’t own a single server or host a digital checkout page.
Modern security relies on tokenization and encrypted data entry. These technologies ensure that sensitive card information never actually touches your local network. When you enter card details into a virtual terminal, the data is instantly turned into a “token” that only the processor can read. This significantly lowers your risk profile. If a hacker were to access your records, they’d find nothing but useless strings of code. Leveraging AI-driven fraud prevention is also vital. These systems analyze thousands of data points in milliseconds to stop chargebacks before they happen, protecting your hard-earned revenue from sophisticated attacks.
PCI Compliance for Small Businesses
PCI DSS (Payment Card Industry Data Security Standard) is a set of rules all merchants must follow. As of 2026, PCI DSS 4.0 is the mandatory standard. It requires stricter authentication, such as multi-factor authentication (MFA), for anyone accessing cardholder systems. Even if you only use a virtual terminal occasionally, these rules apply to you. Choosing a professional payment processor is the most effective way to reduce your compliance burden. They manage the secure infrastructure so you don’t have to. Best practices include never storing card numbers in spreadsheets or on paper. If you’re taking information over the phone, enter it directly into the secure portal while the customer is on the line.
Fraud Prevention Strategies
Success in how to accept payments online without a website requires a proactive defense. Always verify billing addresses through the Address Verification Service (AVS) and require CVV codes for every keyed transaction. These simple steps stop many low-level fraud attempts. You should also implement velocity checks. These automated rules prevent fraudsters from using your terminal to “test” thousands of stolen card numbers in rapid succession. For high-ticket services, 3D Secure adds an essential layer of authentication. It confirms the buyer’s identity through their bank, which can significantly reduce your liability if a transaction is later disputed.
Calculating the Real Cost: Eliminating Processing Fees
When you research how to accept payments online without a website, you’ll quickly notice that processing costs are often higher than at a physical checkout. Banks and processors categorize these as Card-Not-Present (CNP) transactions. Because there’s no physical card to dip or tap, the perceived risk of fraud is higher. To compensate, financial institutions charge a premium. For a high-ticket service provider, these small percentages act as a heavy drain on profit margins. A 3.5% fee on a $10,000 project means $350 vanishes before the money even hits your account. Over a fiscal year, this can cost a lean business tens of thousands of dollars in lost revenue.
You don’t have to accept these fees as an unavoidable cost of doing business. Modern technology allows you to implement a surcharge and dual pricing engine that effectively neutralizes these expenses. This isn’t about increasing your prices across the board; it’s about offering transparency and choice. By using a smart engine, you can automatically calculate the processing cost and apply it only to those who choose the convenience of a credit card. This ensures that your base service rates remain competitive while protecting your bottom line from the rising costs of digital commerce.
The Surcharge Solution for Service Providers
A surcharge is a specific fee added to a credit card transaction to cover the merchant’s processing costs. This differs from a convenience fee, which is typically a flat charge for using a non-standard payment channel. Implementing a zero fee credit card processing model allows you to receive 100% of your invoice amount. As of 2026, state-by-state compliance has become more uniform, but you must still follow specific disclosure rules. Professional virtual terminals handle these requirements for you, displaying the surcharge clearly on the digital receipt so you stay on the right side of the law.
Dual Pricing: A Transparent Alternative
Dual pricing is often the preferred choice for businesses that want to offer a “Cash Discount” experience. You present two prices to the client: a lower price for cash or A2A (Account-to-Account) transfers and a standard price for credit cards. This model is highly effective because it rewards customers for using lower-cost payment methods. Communicating this is simple; just let your clients know that you’re offering a discount for direct payments to keep your service rates low. Data shows that surcharge programs can save merchants up to 4% on every transaction. It’s a powerful way to master how to accept payments online without a website without sacrificing your hard-earned profits.
Eliminating these fees is the final piece of the puzzle for a lean, website-free business. It turns a major recurring expense into a neutral line item. If you’re ready to stop losing a portion of every sale to the banks, explore our surcharge and dual pricing engine to see how much revenue you can reclaim today.
Scaling Your Business with Strictly: The All-in-One Solution
Scaling a professional service requires more than just a way to take money. It requires a partner that understands the specific challenges of remote, service-based commerce. Strictly is the preferred choice for merchants who want to master how to accept payments online without a website because we unify every tool you need into a single, high-performance platform. Instead of juggling different apps for invoicing, security, and fee management, you get an omni-channel ecosystem designed for growth. This unified data approach gives you a clear view of your business health, helping you make smarter decisions as you expand your reach.
Trust is the most valuable currency in 2026. As a dedicated payment processor, we provide the infrastructure that allows you to project a Fortune 500 image regardless of your company size. Our platform integrates AI-driven fraud prevention directly into your workflow, which is essential for protecting the high-ticket transactions common in service industries. By centralizing your payment links, virtual terminal entries, and invoices, you eliminate the data silos that lead to accounting errors. This streamlined operation is the secret to how to accept payments online without a website while maintaining the highest standards of professional reliability.
Strictly’s Virtual Terminal and Invoicing
Our virtual terminal and invoicing suite is built for the modern professional who values time and accuracy. You can seamlessly send professional invoices that customers can pay in one click from any device. We know that following up on payments is often the most frustrating part of the job. Our system includes automated reminders for unpaid bills to improve your cash flow without the need for awkward phone calls. You also gain access to real-time reporting and analytics for all your remote sales. This level of insight ensures you always know which services are driving your revenue and which clients are your most consistent partners.
The Strictly Advantage: Zero-Fee Processing
The most significant barrier to scaling is often the weight of transaction costs that eat into your margins. Strictly’s Smart Pricing Engine automates compliance for surcharge and dual pricing models, allowing you to keep 100% of your sales revenue. By eliminating processing overhead, you can reinvest those funds back into your marketing or operations. We handle the technical heavy lifting of PCI DSS 4.0 compliance and provide the tools to manage your partners effectively. Ready to start? See how much you can save with our cost calculator and discover the most profitable way to manage your business today.
Take Control of Your Revenue Today
Operating a successful business in 2026 doesn’t require the technical burden of a traditional e-commerce site. By leveraging professional virtual terminals and instant payment links, you can meet your customers exactly where they are. We’ve explored how these tools provide immediate access to funds while maintaining the highest security standards. Protecting your margins is just as vital as making the sale. Implementing a surcharge or dual pricing model ensures that those high card-not-present fees don’t drain your profits.
Mastering how to accept payments online without a website allows you to run a leaner, more agile operation. You can focus on delivering exceptional service while your payment infrastructure handles the heavy lifting of compliance and fraud detection. Strictly provides an omni-channel solution that’s ready for the demands of 2026, featuring AI-driven fraud prevention and a platform that’s compliant in all 50 states. It’s time to stop letting transaction costs dictate your growth.
Eliminate your processing fees today with Strictly. You have the knowledge and the tools to build a more profitable future. Start keeping 100% of your hard-earned revenue right now.
Frequently Asked Questions
Is it legal to accept credit card payments without a website?
Yes, it’s completely legal to accept credit card payments without a digital storefront. Regulatory bodies like the PCI Security Standards Council provide clear guidelines for card-not-present transactions. You simply need to ensure your payment processor is compliant with current PCI DSS 4.0 standards. Many service providers operate this way to keep overhead low while maintaining a professional billing process that doesn’t rely on a complex e-commerce site.
How do I send a payment link to a customer?
You send a payment link by generating a unique URL within your merchant dashboard. Once created, you can copy and paste this link into a text message, email, or social media DM. The customer clicks the link and enters their details on a secure page hosted by your processor. It’s a frictionless way to handle how to accept payments online without a website while providing a modern checkout experience.
What is a virtual terminal and how does it work?
A virtual terminal is a web-based application that turns your computer or tablet into a credit card machine. You log into a secure portal provided by your processor and manually enter the customer’s card information. It’s the primary tool for taking orders over the phone or processing mail-in payments. Because it’s cloud-based, you don’t need any physical hardware or a website to get paid securely from any location.
Are online payments safe if I don’t have a secure website?
Online payments are highly secure even without your own website because the security burden shifts to your payment processor. Your processor uses tokenization and encryption to protect sensitive data during the transaction. By using a partner that offers AI-driven fraud prevention, you can detect suspicious patterns in real-time. This setup often provides better protection than a poorly maintained small business website would, as the processor manages all technical compliance.
How much does it cost to accept payments without a website?
The cost typically involves a percentage of the transaction plus a small flat fee. Because these are “Card-Not-Present” sales, the rates are often slightly higher than in-person swipes to account for increased risk. However, you can use a surcharge or dual pricing engine to pass these costs onto the customer. This allows you to keep your full profit margin without the expense of website hosting or monthly maintenance fees.
Can I use a payment link for recurring subscriptions?
Yes, you can easily set up recurring subscriptions using payment links or virtual terminals. Most modern systems allow you to store a secure token of the customer’s card info for future billing without seeing the actual numbers. You can then schedule automated weekly or monthly invoices. This is a great way to manage how to accept payments online without a website for long-term consulting retainers or service contracts.
What is the difference between a surcharge and a cash discount?
A surcharge adds a fee to a credit card transaction, while a cash discount offers a lower price for non-credit payments. Surcharging is a way for merchants to recover the cost of processing fees directly from the cardholder at the point of sale. A cash discount incentivizes customers to use cheaper methods like A2A transfers or checks. A dual pricing engine can manage both models to ensure you stay compliant with state laws.
How long does it take to get funds from a virtual terminal transaction?
Funds from a virtual terminal transaction are typically deposited into your account within one to two business days. The exact timing depends on your processor’s payout schedule and your bank’s specific processing times. Some providers in the industry offer instant payout options for a small additional fee if you need immediate access to your capital. You should check your merchant agreement to see the specific settlement times for your account.